Budgeting Like a Pro: A Guide to Saving and Debt
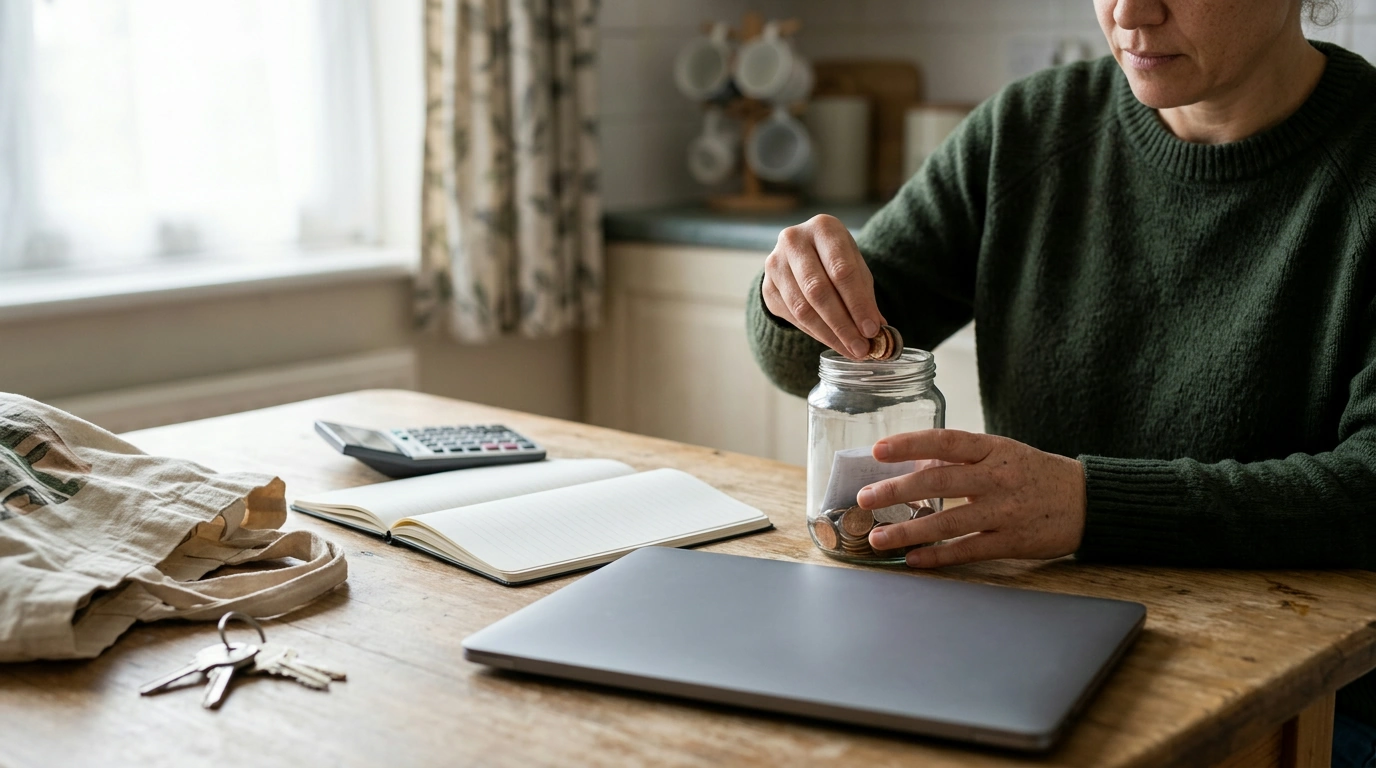
A budget is a plan for using the money you have, not a test you pass or fail. It can help you see how everyday expenses, savings, and debt payments fit together—and give you a starting point when they don’t.
Our Budgeting Like a Pro eBook offers a practical introduction to organizing those priorities. Whether you’re building your first budget or refreshing an old one, start with a clear picture of your finances and choose a method you can return to each month.
Start With a Clear Picture of Your Money
Begin by listing your monthly take-home income: the money that reaches you after taxes and other payroll deductions. If your income varies, use a conservative estimate based on recent months, then decide how you’ll handle any additional income when it arrives.
Next, list what your money needs to cover. Include essential expenses such as housing, utilities, groceries, transportation, and insurance. Add flexible spending, such as dining out and entertainment, along with minimum debt payments and savings goals. Reviewing recent bank and card transactions can help you spot costs you might otherwise overlook.
Look beyond monthly bills, too. Annual subscriptions, car maintenance, gifts, and travel can be easier to manage when you estimate their yearly cost and set aside a portion each month. The Consumer Financial Protection Bureau’s Your Money, Your Goals resources offer additional tools for taking stock of income and expenses.
For a guide to putting the pieces together, explore our Budgeting Like a Pro eBook, listed at $25.99. It covers budgeting methods, debt payoff, and savings planning.
Choose a Budgeting Method That Fits
There’s no single approach that works for every household. The right method is one that reflects your obligations and gives you enough structure to make decisions without making the process harder than it needs to be.
| Method | How it works | Useful when |
|---|---|---|
| Zero-based | Assign each dollar a purpose | You want a detailed plan for your income |
| 50/30/20 | Divide income among needs, wants, and savings or debt repayment | You prefer broad spending targets |
| Pay yourself first | Set aside savings before planning other spending | You want to make saving a regular priority |
With zero-based budgeting, your planned allocations add up to your income. Every dollar gets a job, whether it’s paying a bill, covering groceries, reducing debt, or building savings. Zero left to assign doesn’t mean zero in your bank account.
The 50/30/20 framework uses 50% of income for needs, 30% for wants, and 20% for savings and debt repayment as broad targets. Treat those percentages as a starting point, not a rule: housing costs, income, and other circumstances may call for a different split.
With pay-yourself-first budgeting, you set aside a chosen amount for savings before allocating the rest to spending and other obligations. Pick an amount that leaves enough room for required bills, and revisit it when your circumstances change.
Make Room for Savings and Debt Payoff
You don’t have to fund every goal at once. Start with a savings contribution you can afford, even if it’s modest. A separate emergency fund can give unexpected expenses a place in your plan; the CFPB’s emergency fund guide offers more ideas for getting started.
For debt, keep up with required payments across your accounts. If you have room to pay extra, one approach is to direct that amount toward the highest-interest debt first, which can reduce interest costs over time. Another is to focus on the smallest balance first, which may provide a quicker milestone to build momentum.
Before making extra payments, review your debt terms for fees or other conditions, and consider how the payment affects your cash available for essentials. Your choice can reflect both the numbers and the approach you’re most likely to maintain.
Put Your Plan Into Practice
Set aside time at the beginning of each month to choose your priorities and assign amounts to your categories. During the month, track spending in a notebook, spreadsheet, or another system you’ll actually use. At the end, compare your plan with what happened and decide what needs to change.
If your income shifts or an unexpected expense appears, revise the categories rather than abandoning the budget. You might temporarily reduce a flexible category, adjust a savings contribution, or rebuild a reserve over several months. A useful plan can adapt as your life does.
Planning for a trip? You can include a travel fund in your budget and use our Minimalist Travel Packing Planner to organize what to bring. When you’re ready to work through your broader money plan, our team invites you to explore the Budgeting Like a Pro eBook.
FAQ
What is zero-based budgeting?
Zero-based budgeting assigns all of your income to planned allocations, so income minus those allocations equals zero. Allocations include spending, savings, and debt payments.
Can I combine pay-yourself-first and zero-based budgeting?
Yes. Allocate your chosen savings amount first, then assign the remaining income to expenses, debt payments, and other priorities.
Should I save money or pay off debt first?
Consider balancing a modest emergency cushion with your required debt payments. Interest rates, available cash, and your individual circumstances can help guide how you divide any extra money.


Leave a comment